


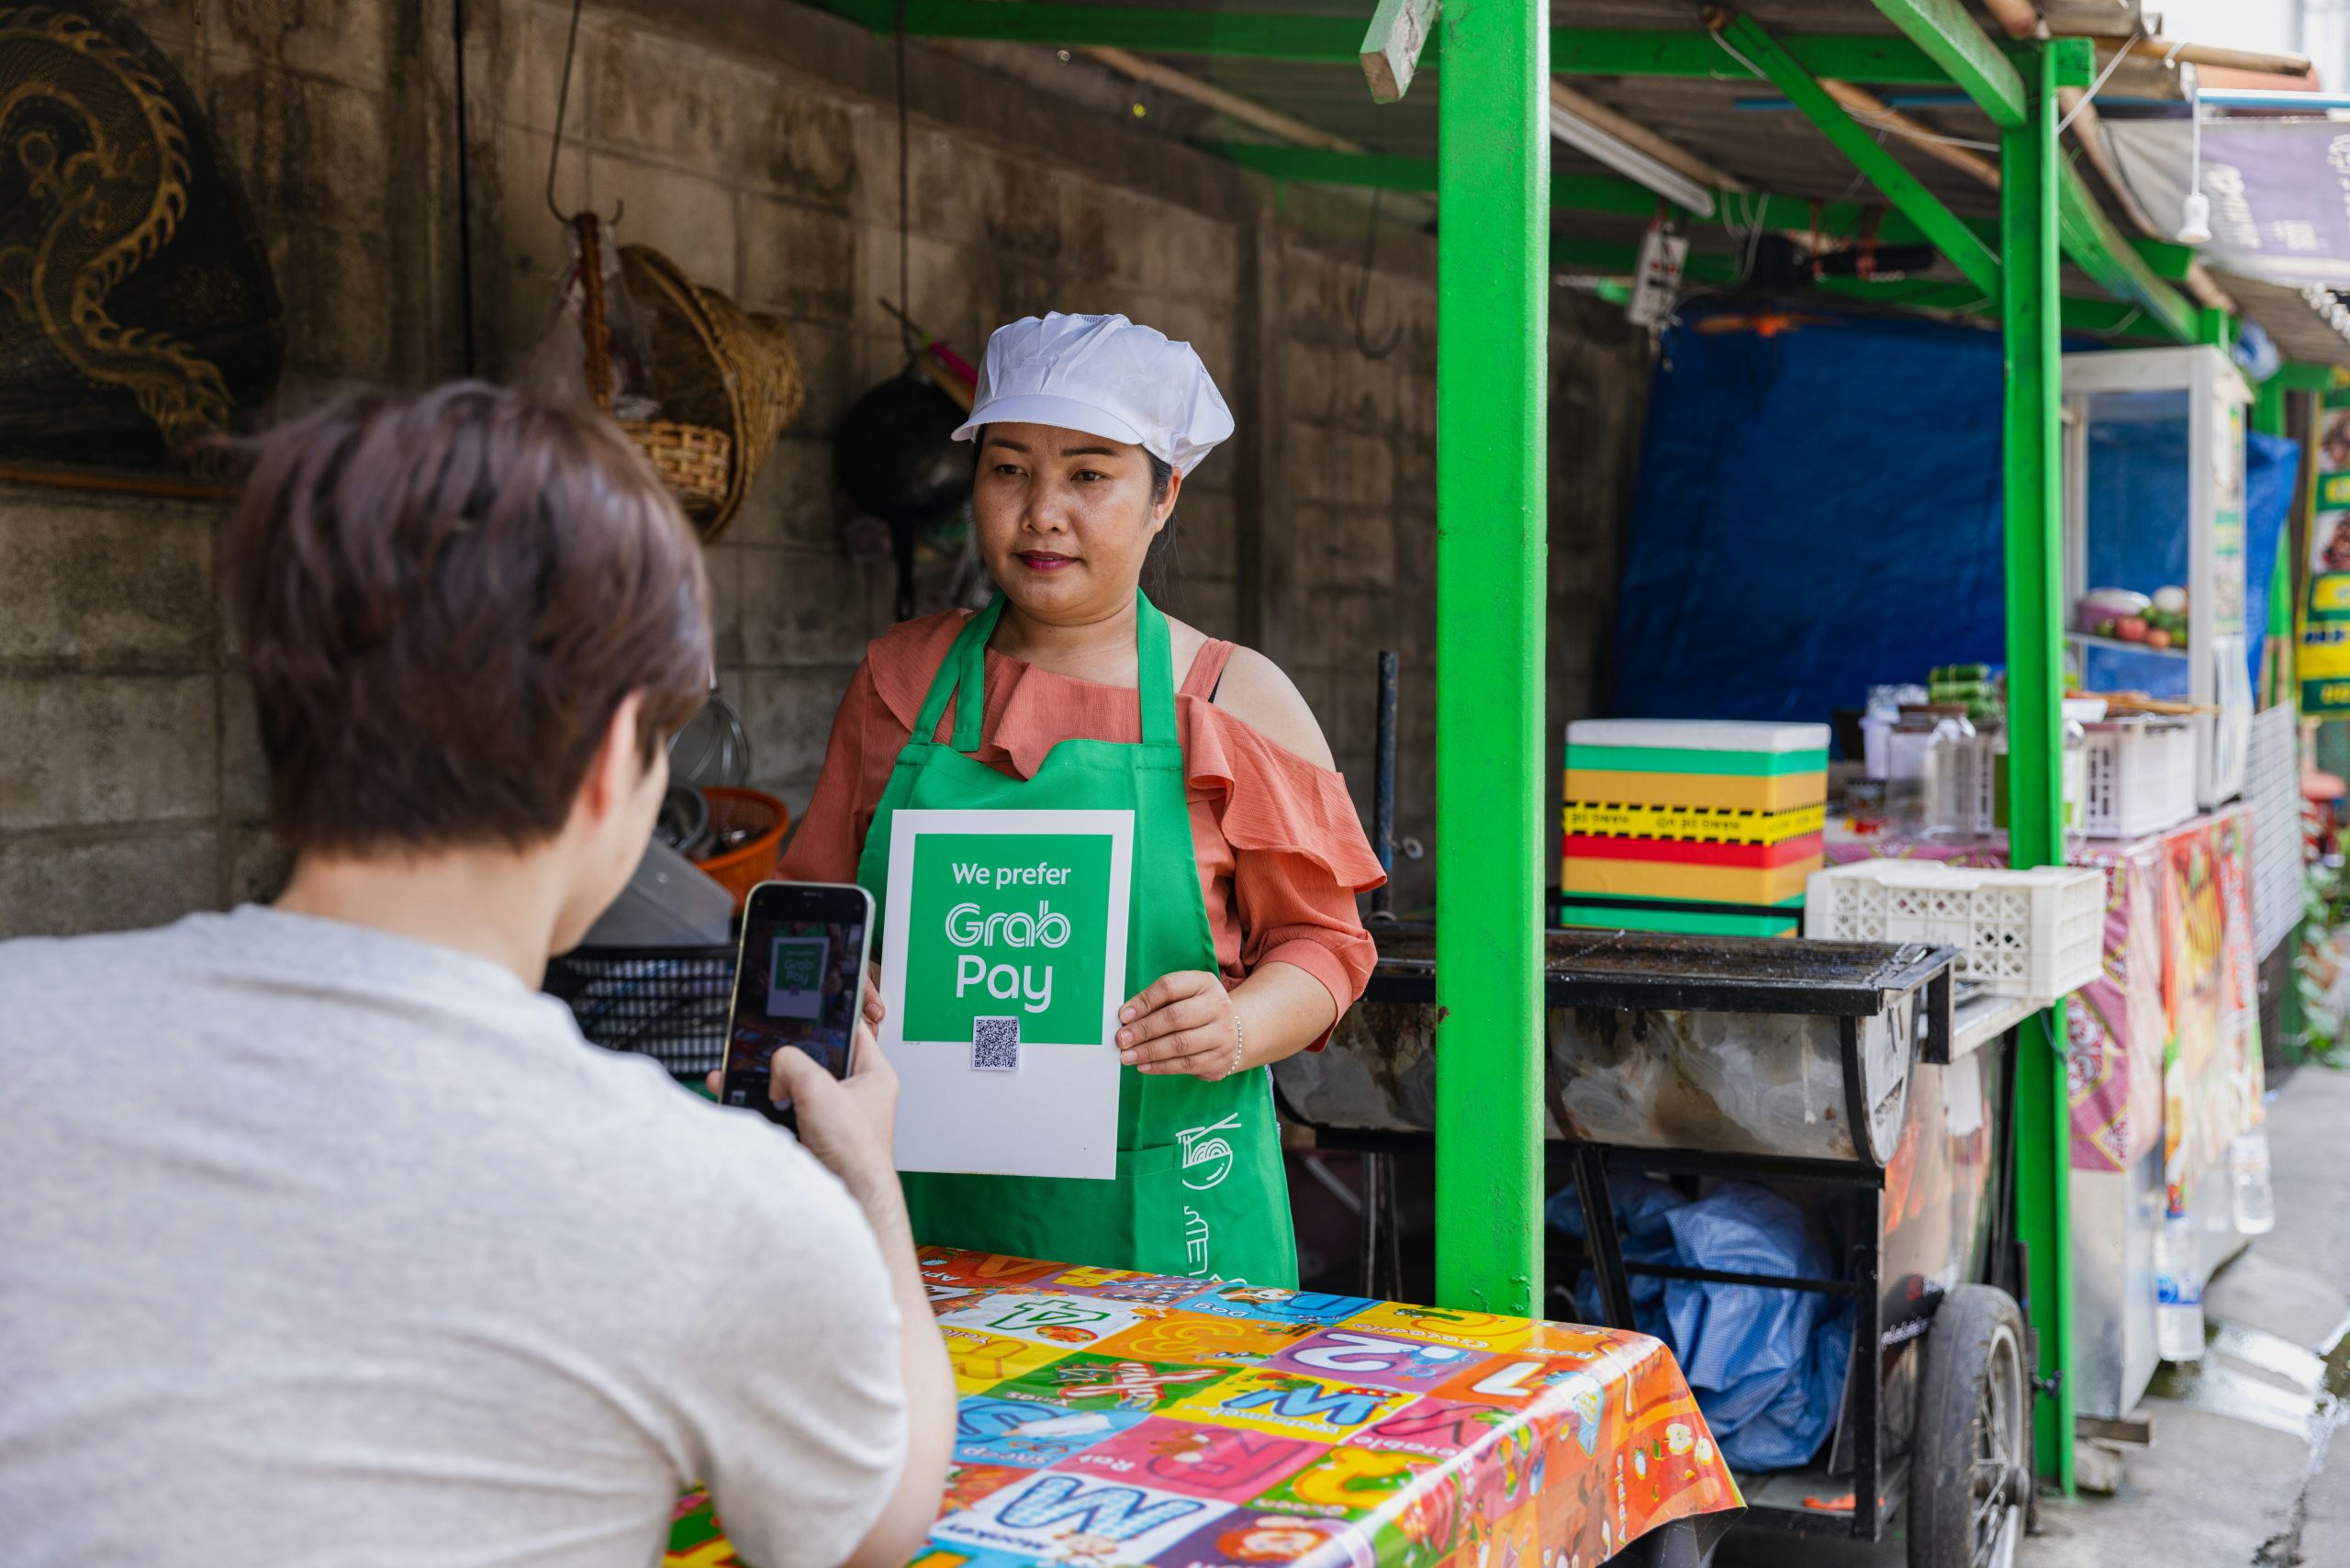
From Convenience to Adoption: Grab’s Next Challenge in Digital Finance
Grab’s acquisition of a 60% stake in Atome Financial for US$1.49 billion marks another step in its ambition to expand beyond mobility and deliveries into everyday financial services. Announced in September 2026, the deal would bring Atome’s buy now, pay later (BNPL) services, consumer loans and digital lending capabilities into Grab’s existing ecosystem. Atome operates across five Southeast Asian markets and brings an established lending platform, while Grab offers a large customer base and extensive regional reach. The transaction is expected to close by the third quarter of 2027, subject to regulatory approvals.
The strategic logic is straightforward: Grab can offer more financial products to customers who already use its platform, while Atome gains access to new distribution channels. But there is a bigger question beneath the deal. Does making financial services more convenient actually make people more likely to use them? For Grab, the opportunity is not simply to expand its product offering, but to persuade consumers to see it as a credible provider of financial services, rather than primarily as an app for getting around and ordering food.
Grab has built a strong presence in consumers’ daily lives, but familiarity with a brand does not automatically translate into trust across every product category. Consumers may happily use Grab for a ride or meal without considering it their first choice for borrowing money. Financial decisions carry different stakes, and people often have established relationships with banks or other lenders they perceive as more credible. This creates a gap between having a financial product available and having consumers actively choose it. For Grab, the challenge is to turn existing customer reach into genuine demand for lending, rather than assume that adoption will follow simply because the service sits within an app people already use.
The acquisition strengthens Grab’s ability to offer a broader range of services, but a wider product portfolio alone does not make an ecosystem indispensable. Consumers need to understand why they should use Grab for each additional service, especially when alternatives are already familiar. Atome brings established lending capabilities and a merchant network, giving Grab a stronger foundation than building everything internally. Yet the combined business must still make its financial services relevant to customers’ needs and establish a clear reason to choose them over competing providers. The next stage of Grab’s super-app ambition will depend as much on changing consumer behaviour as on adding new capabilities.
For lending, credibility is built through more than convenience. Consumers want to understand the cost of borrowing, feel confident that their information is handled responsibly and believe that a provider will support them throughout the repayment process. Familiarity with Grab may help introduce users to its financial products, but it cannot replace these assurances. Grab can strengthen adoption by communicating terms clearly, demonstrating responsible lending practices and showing how its products serve specific customer needs. Over time, positive customer experiences and visible evidence of value can help build confidence. The goal should be to make consumers comfortable choosing Grab for financial decisions, not simply make borrowing easier to access.
Grab’s scale gives it a meaningful starting advantage, but the acquisition’s success should be judged by more than the number of products launched or customers reached. The more important questions are whether consumers try these services, continue using them and see enough value to choose them again. This requires understanding where customers hesitate, what alternatives they trust and which use cases genuinely meet an unmet need. It also means distinguishing between customers who sign up because a product is prominently placed and those who adopt it because it solves a real problem. For Grab, sustained engagement will be a stronger indicator of success than distribution alone.
Ultimately, Grab’s Atome deal makes strategic sense: it adds lending capabilities and creates more opportunities to serve existing customers. But the harder work begins after the acquisition — turning convenience into confidence, and confidence into adoption. For digital platforms expanding into financial services, that is the difference between having a broader ecosystem and building one consumers genuinely want to use.

Related Blogs
Related posts
Stablecoin Payments Are Growing. What Will It Take to Move Beyond Cards?
The Agentic AI paradox in Singapore fintech: Why adoption is outrunning infrastructure
How Thredd’s cloud-native strategy is redefining next-generation card issuing across APAC
How PayNow Gen2 is rewriting Singapore’s digital infrastructure

